Author: Rohan Tamang

  • Nasdaq Ends October With Its Worst Month Since March 2025 as Tech Sell-Off Deepens

    Nasdaq Ends October With Its Worst Month Since March 2025 as Tech Sell-Off Deepens

    Introduction

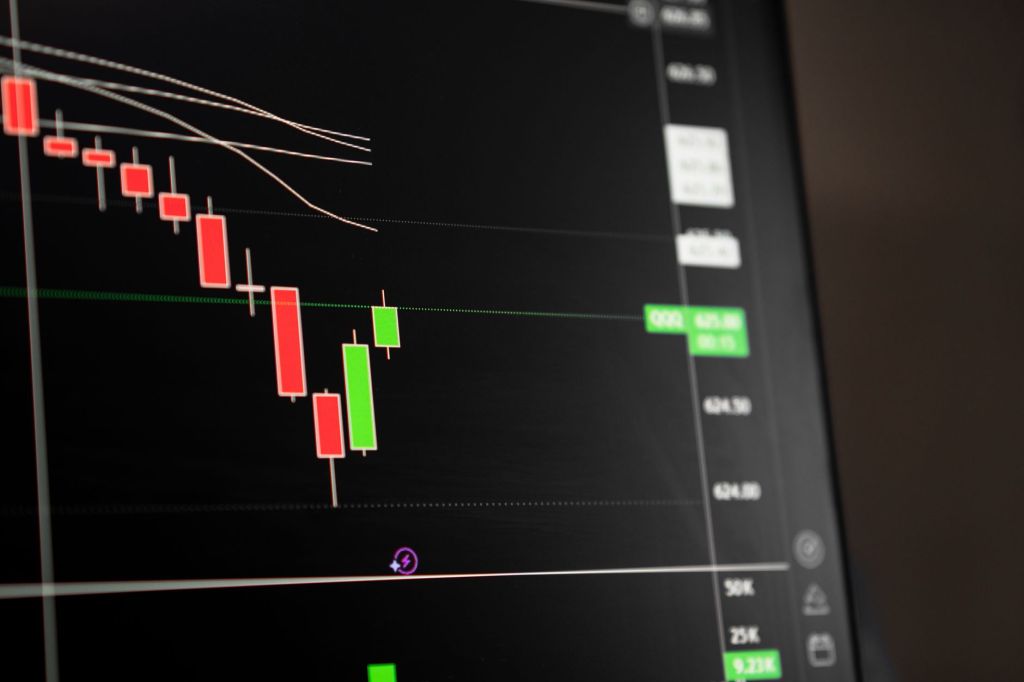
    October ended badly for tech stocks. On Friday, October 30, the Nasdaq Composite fell 2.9% to 25,437, the S&P 500 dropped 1.8% to 7,580, and the Dow Jones fell 1.1% to 51,770. For the full month, the Nasdaq lost more than 5%, its worst month since March 2025.

    What Happened

    The day’s biggest loser was Intel. Its shares plunged 28.6% to $65.76, the worst single day for the stock since the 1970s, according to CNBC reporting. The fall came after Intel gave a weak forecast for the fourth quarter, with revenue of $15 billion to $16 billion, below the roughly $17.1 billion Wall Street expected.

    The pain spread across the chip sector. Qualcomm fell 11.1%, Nvidia dropped 4.2%, AMD lost about 11%, and SanDisk fell 13.5%. The Nasdaq 100, which tracks the largest tech stocks, fell 3.5%.

    Amazon also slipped 1.4% after its own disappointing results the night before. Alphabet, which had already fallen 12.6% on Thursday in its worst day on record, dropped another 1.4% on Friday.

    Not everything fell. Six of the eleven sectors in the S&P 500 actually rose. Energy gained 1.9% and consumer staples rose 1.4%, as investors moved money into safer, steadier businesses. Exxon Mobil and Chevron both briefly hit record share prices after strong earnings helped by refining profits.

    Why It Happened

    The simple story is this: investors are no longer willing to pay any price for AI spending. For months, big tech companies have been pouring hundreds of billions of dollars into data centres and chips. Now investors want to see the money coming back.

    This week gave them reasons to doubt. Alphabet reported negative free cash flow. Amazon kept its 2026 spending plan at about $220 billion while reporting negative free cash flow of $42.4 billion over the past twelve months. Intel’s weak outlook suggested that even chipmakers are feeling pressure from a soft PC market and rising memory prices.

    When a company that has already risen about 150% this year, as Intel had, disappoints on its outlook, the fall can be brutal.

    Why It Matters

    A few numbers put the week in context:

    • The Nasdaq is now down 7.8% from its all-time closing high on October 6.
    • For the week, the Nasdaq finished down 2%, the S&P 500 down 0.6%, and the Dow down 0.9%.
    • For October, the Dow still gained 1.5%, but the S&P 500 lost 1.2%.
    • Technology stocks lost more than $1 trillion in market value during Friday’s sell-off alone, according to market reports.

    The split inside the market matters too. When energy, staples and utilities rise while tech falls, it tells you investors are not panicking about the whole economy. They are repricing one specific bet: the AI trade.

    What Happens Next

    All eyes now turn to next week. Apple reports earnings, the October jobs report arrives, and 138 S&P 500 companies are scheduled to report results. Investors will also be watching the US midterm elections on Tuesday.

    If upcoming earnings show that AI spending is starting to pay off, tech could steady itself. If more companies disappoint, the sell-off could continue. Either way, the days when any AI announcement pushed a stock higher appear to be over, at least for now.

    Final Thoughts

    October was a reminder of a basic investing lesson: price matters. Great technology does not automatically mean a great stock at any price. When expectations get too high, even a decent quarter is not enough. Investors are now asking a harder question of every tech company: not “are you spending on AI?” but “when will that spending make money?”

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC market coverage of the October 30 sell-off: https://www.cnbc.com/2026/10/30/amazon-intel-earnings-big-tech-ai-spending-concerns.html; market-wrap reporting of October 30 closing prices: The Edge (https://edgeconsultancykw.com/us-market-wrap-30-october-2026/) and Market Briefer (https://marketbriefer.com/the-global-close-october-30-2026-intels-worst-day-in-52-years-caps-the-ai-rout/).
  • Nasdaq Falls 3% as Tech Sell-Off Deepens — Worst Day Since June

    Nasdaq Falls 3% as Tech Sell-Off Deepens — Worst Day Since June

    Tech stocks took a hard hit on Friday, October 30. The Nasdaq composite fell 3% during the day, putting Wall Street on track for its worst day since June. The sell-off was led by big technology names, and it came right after a rough week for the same stocks.

    The numbers below are from trading during the day, not the final closing numbers. Markets were still open when these figures were reported, so the final results may look a little different.

    What Happened

    The Nasdaq composite dropped 3% as of early afternoon Eastern time. The S&P 500 fell 1.8%, and the Dow Jones Industrial Average dropped 496 points, or 0.9%.

    The Nasdaq 100, which tracks the 100 largest non-financial companies on the Nasdaq, also fell about 3%. Reuters reported it was on course to lose just over $1 trillion in market value on the day.

    Not every stock fell. Defensive stocks — the kind of companies people turn to when they want safety — actually rose. Walmart, Coca-Cola, and Procter & Gamble all moved higher while chipmakers dropped.

    Why It Happened

    Two earnings reports from Thursday night set the tone: Intel and Amazon.

    Intel fell about 29% after it gave a weak forecast for the fourth quarter. The company said the slowdown in personal computer sales should last at least through the first half of next year. It also pointed to manufacturing problems, a memory chip shortage, and heavy spending to expand production. Reuters said the stock was set for its biggest one-day loss on record.

    Amazon fell about 2% during the day, after dropping as much as 10% in after-hours trading on Thursday. The company reported quarterly capital spending of $77.3 billion, much higher than the $58.7 billion analysts expected. That spending is mostly going toward building artificial intelligence infrastructure — data centers, chips, and computing power.

    Other chip stocks fell too. Nvidia dropped almost 4%, and AMD lost more than 9%.

    This came one day after Google’s parent company Alphabet had its worst day ever on Thursday, falling 12.6%. Alphabet slipped about 1% more on Friday. Earlier this week, we covered that drop in detail: Why Google Stock Crashed 12.6%: What Investors Need to Know.

    Key Figures

    • Nasdaq composite: down 3% during Friday trading
    • S&P 500: down 1.8%, on track to erase its gain for October
    • Dow Jones: down 496 points, or 0.9%
    • Intel: down about 29% after a weak fourth-quarter forecast
    • Amazon: down about 2%, after capital spending of $77.3 billion beat expectations of $58.7 billion
    • Nvidia: down almost 4%; AMD: down more than 9%
    • Nasdaq 100: on course to lose just over $1 trillion in market value on the day

    Why It Matters

    The bigger worry here is simple: companies are spending huge amounts of money on AI, and investors are starting to ask when that spending will pay off.

    Think of it like this. Imagine a restaurant owner borrows a lot of money to build a second location. If customers start coming in quickly, the bet pays off. But if the new location sits half-empty while the loan payments pile up, investors get nervous. That is roughly what is happening with AI right now. Tech giants are pouring tens of billions into data centers and chips, and the market wants proof that the returns will come soon enough.

    October has already been a rough month for tech. Through Thursday’s close, the Nasdaq 100 was down 3.31% for the month, on track for its first monthly decline in three months, even though it is still up more than 16% for the year.

    At the same time, the S&P 500 was on track to erase its entire gain for October, even though it set an all-time high earlier in the month. That shows how fast sentiment can change.

    What Happens Next

    A few things to watch. First, the final closing numbers for Friday — the early-afternoon figures above will be updated once trading ends. Second, more big tech earnings are still to come, including Apple and Meta, which could either calm the market or add to the selling. Third, investors will keep a close eye on whether companies start talking about slowing down their AI spending, or whether they double down.

    It is also worth remembering that a 3% drop, while sharp, does not erase the year’s gains. The Nasdaq 100 is still well up for 2026. Big down days happen, even in strong years.

    Final Thoughts

    Friday’s sell-off is a reminder that even the strongest market trend can reverse quickly when expectations get too high. Investors loved the AI story all year, but now they want to see the profits behind the spending. Intel’s weak forecast and Amazon’s huge spending bill gave them a reason to step back.

    For everyday investors, the lesson is not to panic over one bad day. It is to check whether the companies you own are actually making money from their big bets — or just spending more and hoping.

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC — Stock market today live updates, Associated Press via Barchart — tech sell-off drags Nasdaq down 3%, Reuters coverage of the Nasdaq 100’s $1 trillion market value drop

  • JPMorgan Turns Bullish on Palantir With a $262 Target Ahead of Earnings

    JPMorgan Turns Bullish on Palantir With a $262 Target Ahead of Earnings

    Introduction

    JPMorgan just gave Palantir a strong vote of confidence. The bank started coverage of the AI software company with an Overweight rating and a 12-month price target of $262, about 33% above its Wednesday closing price.

    What Happened

    JPMorgan initiated coverage of Palantir on Thursday, October 29, with an Overweight rating. In simple terms, Overweight means the bank expects the stock to do better than the market average. The $262 target is roughly one-third higher than where the shares closed on Wednesday.

    JPMorgan also placed Palantir on its Positive Catalyst Watch ahead of the company’s third-quarter results, which are due after the market closes on Monday, November 2.

    Key figures

    • JPMorgan rating: Overweight (new coverage)
    • JPMorgan 12-month price target: $262, about 33% above the Wednesday close
    • Third-quarter results due: Monday, November 2, after the market close
    • Analyst consensus for Q3 revenue: $2.18 billion, up about 85% year over year
    • Palantir’s own Q3 revenue guidance: $2.160 billion to $2.164 billion
    • Palantir’s full-year 2026 revenue guidance: $8.150 billion to $8.158 billion
    • Wall Street view: 26 of 35 analysts tracked by LSEG rate the stock Buy or Strong Buy
    • Recent run: shares up 59% in the past three months, though they have trailed the S&P 500 so far in 2026

    Why It Happened

    JPMorgan analyst Brian Essex argued that big companies are moving past the early stage of AI, where they were just deciding how to use it. Now they want to see real, measurable returns from their AI spending. In his view, Palantir is already delivering those returns by helping clients run their businesses better, and its growth is accelerating.

    Palantir sells software that helps governments and companies organise large amounts of data and make decisions from it. As AI becomes a bigger part of everyday business, JPMorgan believes demand for that kind of platform will keep growing.

    Why It Matters

    Analyst ratings do not guarantee a stock will rise, but a new Overweight call from a major bank still matters. It can bring fresh attention to a stock, especially just before earnings. It also shows a split in Wall Street opinion: while JPMorgan is bullish, other analysts remain cautious about Palantir’s high valuation, with at least one firm holding a sell rating and a much lower target.

    For regular investors, the useful lesson is not the target price itself. It is the question behind it: are companies actually making money from AI, or just spending money on it? Palantir’s results on November 2 will be one test of that question.

    What Happens Next

    All eyes turn to Monday’s earnings report. Investors will compare revenue with the $2.18 billion consensus and Palantir’s own guidance, and they will listen closely to what management says about the rest of the year. A strong outlook could support JPMorgan’s bullish view. A weak one could quickly reverse it.

    Final Thoughts

    JPMorgan is betting that Palantir is moving from AI promise to AI profit. On Monday, the numbers will show whether that bet is on track.

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC coverage of JPMorgan’s Palantir call | Barchart, “Ahead of Palantir Earnings,” Oct. 30, 2026.

  • Shell Profit Nearly Doubles to $10.8 Billion on Record Refining Margins

    Shell Profit Nearly Doubles to $10.8 Billion on Record Refining Margins

    Introduction

    Shell just reported one of its strongest quarters in years. Adjusted earnings nearly doubled to $10.8 billion, helped by record refining margins, and the company is returning more cash to shareholders with a bigger buyback.

    What Happened

    Shell reported third-quarter adjusted earnings of $10.81 billion, up from $5.43 billion a year earlier and $9.84 billion in the second quarter. That beat the $9.92 billion consensus compiled by LSEG and cited by CNBC, and it was Shell’s strongest quarterly profit since the second quarter of 2022.

    Income attributable to shareholders was $12.1 billion. Cash flow from operations was $21.0 billion, and free cash flow was $16.3 billion. Net debt fell to $39.7 billion at the end of the quarter, down from $41.8 billion in the second quarter.

    Shell also announced a $5 billion share buyback programme for the next three months, up from $3 billion in the previous quarter. A buyback means the company buys its own shares back, which reduces the number of shares in circulation and can support the share price.

    Key figures

    • Adjusted earnings: $10.81 billion, vs $5.43 billion a year ago and $9.92 billion expected
    • Income attributable to shareholders: $12.1 billion
    • Cash flow from operations: $21.0 billion
    • Free cash flow: $16.3 billion
    • Global indicative refining margin: $42 per barrel, vs $24 in Q2
    • New buyback: $5 billion over three months, vs $3 billion previously
    • Net debt: $39.7 billion, vs $41.8 billion in Q2
    • Full-year cash capital expenditure outlook: $23–$25 billion, vs $24–$26 billion before

    Why It Happened

    Refining was the driver. Shell’s global indicative refining margin hit a record $42 a barrel, up from $24 in the second quarter. Its Chemicals and Products division earned $3.86 billion, up from $2.88 billion in the previous quarter.

    Shell also benefited from higher realised liquefied natural gas (LNG) prices and stronger Integrated Gas volumes. Integrated Gas earned $3.04 billion. CEO Wael Sawan pointed to strong operational performance in a volatile commodity price environment.

    Why It Matters

    Shell’s result fits a clear pattern this earnings season: oil majors are making big money from turning crude into fuel, not just from producing crude. When refining margins are at record levels, the downstream business can carry the whole company.

    The bigger buyback also matters. It signals that Shell’s management believes the cash flow is strong enough to return more money to shareholders right now, rather than holding it back or spending it all on new projects. Shell also trimmed its full-year spending outlook, which shows some discipline on costs.

    What Happens Next

    Shell will release its full-year 2026 results on February 4, 2027. The new $5 billion buyback is expected to be completed by that announcement. Investors will watch whether refining margins stay near record levels, or whether they fall back as fuel supplies recover.

    Final Thoughts

    Shell turned a record refining quarter into a near-doubling of profit and a bigger payout to shareholders. Like its rivals, the test ahead is whether these margins are a new normal or a temporary windfall.

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC coverage of Shell’s third-quarter results | Shell press release, third quarter 2026 results, Oct. 29, 2026 | Motley Fool, “Shell Profit Leans on Record Refining Margins,” Oct. 29, 2026.

  • BP Posts Record $8.46 Billion Profit and Will Use It to Clear Its Deepwater Horizon Bill

    BP Posts Record $8.46 Billion Profit and Will Use It to Clear Its Deepwater Horizon Bill

    Introduction

    BP just had its best quarter in years. The British oil company reported a third-quarter profit of $8.46 billion, beating expectations, and it plans to use some of that windfall to finally settle the remaining bill from the 2010 Deepwater Horizon disaster.

    What Happened

    BP reported third-quarter underlying replacement cost profit — its version of net income — of $8.46 billion. That beat analysts’ expectations of $7.33 billion in a company-provided poll, and it was up sharply from $2.2 billion a year earlier. It was the highest quarterly profit under BP’s current version of this measure, and its highest in at least five years.

    Operating cash flow came in at $14.8 billion. Net debt fell to $13.9 billion, which means BP reached its net debt target a year ahead of schedule.

    Key figures

    • Underlying replacement cost profit: $8.46 billion, vs $7.33 billion expected and $2.2 billion a year ago
    • Operating cash flow: $14.8 billion
    • Net debt: $13.9 billion, down $8.4 billion, reaching its target a year early
    • Deepwater Horizon payables and provisions still outstanding: $5.94 billion, on a payment schedule stretching to 2033
    • Total amount set aside for the spill over time: about $69 billion

    Why It Happened

    The same story as the other oil majors: higher energy prices and record refining margins. Conflicts disrupted fuel supplies and pushed up prices, which lifted profits across the industry. Shell, Exxon and Chevron all reported strong quarters for the same reason.

    Why It Matters

    The most important part of BP’s announcement is not just the profit number. It is what BP plans to do with the money. The company said it will use excess cash flow to settle its remaining Deepwater Horizon liabilities in full.

    That disaster happened in 2010, when a blowout on the BP-operated Macondo well in the Gulf of Mexico caused one of the worst oil spills in history and killed 11 people. BP has set aside about $69 billion related to the spill over the years. About $5.94 billion in payables and provisions still remain, on a schedule that stretches to 2033. Paying that off early would close a painful chapter for the company and remove a long-running financial burden.

    BP CEO Meg O’Neill said the company is still carrying more debt than it can afford in a low-price scenario, and it is focused on bringing debt down to protect the dividend.

    What Happens Next

    BP will hold a long-term strategy update on December 15. Investors will look for details on how much of the Deepwater bill will be paid early, and how BP plans to balance debt reduction, dividends and investment in its core oil and gas business after its strategy reset in 2025.

    Final Thoughts

    A record profit is good news on its own. Using it to clear a 16-year-old liability is even more meaningful. If BP follows through, it will enter 2027 with a cleaner balance sheet and one less shadow from its past.

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC coverage of BP’s third-quarter results | Reuters, “BP beats forecasts with record profit, targets early settling of Deepwater Horizon bill,” Oct. 30, 2026.

  • Exxon Refineries Earn More Than Its Oil Wells for the First Time in Six Years

    Exxon Refineries Earn More Than Its Oil Wells for the First Time in Six Years

    Introduction

    ExxonMobil just reported a quarter where its refineries made more money than its oil wells. That has not happened in at least six years. The shift helped Exxon beat Wall Street expectations for the third quarter of 2026.

    What Happened

    Exxon reported net income of $15.4 billion, or $3.72 per share, for the third quarter. On an adjusted basis, earnings were $17.5 billion, or $4.23 per share. That beat the average analyst expectation of $4.08 per share compiled by LSEG.

    Revenue reached $113.16 billion, above the $105.24 billion analysts had expected. Exxon also announced a $20 billion share repurchase programme for 2027, the same size as in 2026, and declared a dividend of $1.07 per share, payable December 10.

    Key figures

    • Net income: $15.4 billion ($3.72 per share)
    • Adjusted earnings: $17.5 billion ($4.23 per share), vs $4.08 expected
    • Revenue: $113.16 billion, vs $105.24 billion expected
    • Adjusted downstream (refining) earnings: $9.0 billion, up 120% from the previous quarter
    • Adjusted upstream (production) earnings: $7.3 billion, down 20% from the previous quarter
    • Energy Products segment earnings: $7.17 billion, vs $7.09 billion upstream
    • Production: 4.5 million barrels of oil equivalent per day, roughly flat from Q2

    Why It Happened

    Refining margins surged. Wars and strikes on refineries disrupted global fuel supplies, which pushed up petrol and diesel prices. Exxon’s US Gulf Coast refineries ran at 100% crude-unit utilisation and reached their second-highest diesel production level on record.

    At the same time, upstream earnings fell 20% from the previous quarter because benchmark oil prices were lower than in the second quarter. So the two parts of the business moved in opposite directions, and refining came out on top.

    Exxon CEO Darren Woods told CNBC that diesel is the key crunch point in the global fuel shortage, because diesel is critical to economic growth and demand stays high even when capacity is tight. He said Exxon will keep investing several billion dollars in refineries and expects to increase distillate throughput by about 100,000 barrels a day.

    Why It Matters

    Think of Exxon as two businesses in one. One pulls oil out of the ground. The other turns oil into fuel. Usually the first business makes more money. This quarter the second one did, which shows how much fuel markets have changed.

    For investors, it is a reminder that big oil companies are not just a bet on the oil price. Refining, trading and chemicals can balance the business when oil prices fall. For consumers, it is a sign that diesel shortages are still a real problem in the world economy.

    What Happens Next

    Exxon reduced debt by $8 billion during the quarter. It plans to stick with a sustainable and growing dividend. Investors will watch two things: whether refining margins stay strong, and whether oil production earnings recover if crude prices rise again.

    Final Thoughts

    Exxon’s quarter tells a clear story. When fuel is scarce, the company that can turn crude into fuel quickly wins. The next test is whether that advantage lasts once supply problems start to clear.

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC interview with Exxon CEO Darren Woods and coverage of Exxon’s results | Reuters, “ExxonMobil beats third-quarter profit estimates on refining boom,” Oct. 30, 2026.

  • Chevron Profit Nearly Triples to $9.9 Billion as Refining Boom Lifts Earnings

    Chevron Profit Nearly Triples to $9.9 Billion as Refining Boom Lifts Earnings

    Introduction

    Chevron made a lot more money this quarter than it did a year ago. The oil giant reported third-quarter earnings of $9.9 billion, up from $3.5 billion in the same period last year. Strong refining margins did most of the heavy lifting.

    What Happened

    Chevron reported earnings of $9.9 billion, or $5.06 per share, for the third quarter of 2026. On an adjusted basis, which strips out one-off items, earnings were $10.4 billion, or $5.28 per share. That beat the average analyst expectation of $4.89 per share, according to LSEG data reported by CNBC.

    Total revenue and other income reached $67.8 billion, up from $49.7 billion a year earlier. Cash flow from operations rose to $16.0 billion, and free cash flow reached $12.0 billion, more than double the $4.9 billion from a year ago.

    Key figures

    • Reported earnings: $9.9 billion ($5.06 per share), vs $3.5 billion ($1.82) a year ago
    • Adjusted earnings: $10.4 billion ($5.28 per share), vs $4.89 expected
    • Total revenue and other income: $67.8 billion, vs $49.7 billion a year ago
    • Downstream (refining) earnings: $4.93 billion, vs $1.14 billion a year ago
    • Upstream (oil and gas production) earnings: $5.7 billion, vs $3.3 billion a year ago
    • Free cash flow: $12.0 billion, vs $4.9 billion a year ago

    Why It Happened

    The main reason is refining. When a company refines crude oil into petrol, diesel and jet fuel, it earns the difference between the price of crude and the price of the finished fuel. That gap, called the refining margin, was very wide this quarter.

    Global fuel supplies were tight. Conflicts disrupted refineries and fuel shipments, which pushed up diesel and jet fuel prices. Chevron’s US refineries ran at about 98% of capacity and processed a record just over 1 million barrels of crude oil a day. Diesel and jet fuel yields rose by more than 10%.

    Oil and gas production also helped. Upstream earnings rose about 70% to $5.7 billion, supported by higher crude prices. Brent crude, the global benchmark, averaged $97 a barrel during the quarter, up from $69 a year earlier.

    Why It Matters

    Refining is usually the smaller, steadier part of an oil company. This quarter it became a major profit engine. That matters for investors because it shows Chevron can make strong money even when its oil production business is not the main driver.

    It also matters for everyday life. Tight diesel supplies affect trucking, farming and shipping costs, and those costs often find their way into the price of goods. Strong refining profits are a sign that fuel markets are still under pressure.

    What Happens Next

    Chevron cut its total debt by $3.5 billion during the quarter, to $33.5 billion, and repurchased $2.5 billion of stock. The company said it plans to keep investing in a tight energy market. Investors will now watch whether refining margins stay wide or start to fall back as supply problems ease.

    Final Thoughts

    This was a strong quarter for Chevron, and refining was the star. The question now is simple: was this a one-off boost from tight fuel markets, or can the company keep it going? The next few quarters will give the answer.

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC coverage of Chevron’s third-quarter results | Chevron press release, “Chevron reports third-quarter 2026 results” | Reuters reporting on Exxon and Chevron earnings, Oct. 30, 2026.

  • Burger King’s Comeback Lifts Restaurant Brands, but Popeyes Still Lags

    Burger King’s Comeback Lifts Restaurant Brands, but Popeyes Still Lags

    Introduction

    Restaurant Brands International, the company behind Burger King, Tim Hortons, and Popeyes, reported mixed third-quarter results: profit slightly beat expectations, revenue slightly missed them. The real story was the split inside the company — Burger King is booming, Popeyes is still struggling.

    What Happened

    Revenue rose 3.1% to $2.53 billion, just below the $2.54 billion analysts expected. Adjusted earnings per share came in at $1.10, ahead of the $1.09 forecast and up 6.9% from $1.03 a year earlier. Net income attributable to shareholders jumped to $542 million, or $1.54 per share, from $315 million, or 96 cents, a year earlier. Shares fell about 2% in morning trading after the report.

    Across all its restaurants, same-store sales grew 3.8%, the fifth straight quarter above 3%. System-wide sales grew 6.2%, and the company ended the quarter with 33,401 restaurants in more than 120 countries.

    The brand breakdown tells the story. Burger King US same-store sales surged 8.4%, and management said the brand has reclaimed the No. 2 spot in the US burger category. Tim Hortons Canada grew 1.8%. International same-store sales rose 3.9%, the 22nd straight quarter of growth. Popeyes US same-store sales fell 2.2%.

    Why It Happened

    Burger King’s turnaround, called “Reclaim the Flame,” is a multiyear effort focused on better food, remodelled restaurants, and improved operations. It is now clearly working in the US: 8.4% growth is roughly two and a half times the 3.2% the brand posted in the same quarter last year. Burger King nugget sales have also risen more than 35% since the September 1 relaunch with 100% white meat chicken. The company also picked up refranchising — selling company-owned restaurants to franchisees — with 135 refranchised so far this year.

    Popeyes faces a different problem: tough competition. Rival chicken chains have been drawing customers with discounts, and Popeyes’ recovery is taking longer than management previously hoped. The company no longer expects Popeyes to return to positive same-store sales in the second half of 2026, although traffic is improving.

    Why It Matters

    Restaurant Brands is a useful example of why a company’s overall result can hide two different stories. The group beat on profit because Burger King and the international business are strong. But Popeyes shows that a turnaround in one brand does not automatically fix another — each chain has its own customers, competitors, and problems.

    For Burger King fans and investors, the 8.4% number matters because it shows the turnaround is not a one-quarter fluke. Five straight quarters of group same-store sales above 3% suggests the improvement is broad, not just a promotion-driven blip.

    What Happens Next

    Management reaffirmed that 2026 is on track for 8% organic adjusted operating income growth, and said refranchising will accelerate into 2027, with a couple of hundred restaurants expected to be refranchised this year. The company also declared a fourth-quarter dividend of $0.65 per share, payable January 5, 2027, and returned $569 million to shareholders during the quarter.

    For Popeyes, the watch item is simple: when does the decline stop? Management has stopped promising a quick return to growth, so investors should expect a longer, slower fix built on operations and core menu focus rather than a sudden bounce.

    Final Thoughts

    This was a good quarter powered by one brand. Burger King’s comeback is real and it is carrying the group, while Popeyes remains the weak spot. Restaurant Brands’ challenge now is to prove it can fix its second problem as well as it fixed its first.

    Key figures

    • Revenue: $2.53 billion, up 3.1% (expected: $2.54 billion)
    • Adjusted EPS: $1.10 (expected: $1.09; last year: $1.03)
    • Same-store sales: +3.8% group-wide; Burger King US +8.4%; Popeyes US −2.2%; International +3.9%
    • System-wide sales growth: 6.2%
    • Restaurants: 33,401 in 120+ countries
    • Net income: $542 million (was $315 million)
    • Q4 dividend: $0.65 per share, payable January 5, 2027

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC — https://www.cnbc.com/2026/10/29/restaurant-brands-international-qsr-q3-2026-earnings.html — and the Restaurant Brands Q3 2026 earnings call transcript.

  • Ford Beats Earnings Expectations, but Warns 2027 Profit Will Be Flat

    Ford Beats Earnings Expectations, but Warns 2027 Profit Will Be Flat

    Introduction

    Ford reported a better third quarter than Wall Street expected and nudged its full-year profit outlook higher. Then it gave investors the news they did not want: next year’s profit will probably be no better than this year’s, because rising costs are eating into gains.

    What Happened

    Ford reported revenue of $49.5 billion for the third quarter, down 2% from a year earlier but ahead of forecasts of about $48.9 billion. Adjusted earnings per share came in at 49 cents, beating the 40 cents analysts expected. Adjusted operating profit (EBIT) rose 3% to $2.7 billion, about $300 million ahead of consensus. Net income was $2 billion, down $400 million from a year earlier, and adjusted free cash flow was $4.7 billion.

    By segment: Ford Blue, the traditional gas and hybrid vehicle business, earned about $1.4 billion, down 10% from a year earlier. Ford Pro, the commercial business, earned about $1.7 billion, down 16%. Model e, the electric vehicle unit, lost about $1.1 billion — still a loss, but 25% smaller than a year ago.

    Ford raised the bottom end of its 2026 adjusted EBIT guidance to $10.5 billion–$11 billion, from $10 billion–$11 billion. Free cash flow guidance of $6 billion–$7 billion did not change.

    The stock’s reaction told the story of the outlook. Shares rose about 2% on the day of the report, then slipped about 2% the next morning as investors digested the 2027 warning.

    Why It Happened

    The beat came from strong demand for trucks and SUVs, which carried the traditional business even as costs rose. But the cost side is getting worse, not better. Ford said commodity headwinds are now approaching $2.5 billion for 2026, up from just over $2 billion expected before. Inflation linked to the war in Iran has pushed up logistics, raw materials, and chip costs, and high gas prices are adding to freight and energy bills.

    For 2027, Ford expects about $2 billion of additional pressure from commodities, memory chips, and logistics. That is why profit is expected to be roughly flat next year — the company has to run faster just to stand still.

    Why It Matters

    Ford’s warning is a window into a problem facing all carmakers: input costs are rising again, and there is no quick relief. CEO Jim Farley called 2027 a “foundational year” on the way to an 8% adjusted EBIT margin target by 2029, and CFO Sherry House said plainly, “We’re not expecting relief any time soon” from commodity inflation.

    It also shows how Ford’s strategy is shifting. The company scaled back its money-losing EV business in late 2025 to focus on hybrids and more affordable EVs, booking a $19.5 billion loss on that decision. The EV unit is still losing money, but the loss is shrinking, and Ford is aiming for Model e breakeven by 2029 and an 8% adjusted EBIT margin by 2029, up from 6.1% in the first nine months of this year.

    What Happens Next

    Ford’s affordable EV, called Fathom and priced from $28,350, is still scheduled for late 2027. The company also plans to offset cost pressure with $1 billion of material and warranty cost cuts, plus growth from energy storage batteries, software, and services.

    The near-term test is the fourth quarter. Guidance implies operating profit of about $2.2 billion for the final three months, roughly in line with analyst expectations. If Ford hits that, the “flat 2027” story becomes a story about holding ground while costs rage — not a collapse, but not growth either.

    Final Thoughts

    Ford beat expectations and raised its 2026 outlook, which is genuinely good news. But the market looked past the quarter to next year, where $2 billion of cost pressure means profit goes sideways. For investors, the question is no longer whether Ford can execute — it just did — but whether it can outrun inflation long enough for its cheaper EVs and cost cuts to change the maths.

    Key figures

    • Revenue: $49.5 billion, down 2% year over year (beat ~$48.9 billion expected)
    • Adjusted EPS: $0.49 (expected $0.40)
    • Adjusted EBIT: $2.7 billion, up 3%
    • 2026 adjusted EBIT guidance: $10.5–$11 billion (was $10–$11 billion)
    • 2027 outlook: profit roughly in line with 2026
    • 2027 cost headwind: ~$2 billion; 2026 commodity headwind: ~$2.5 billion
    • Model e Q3 loss: ~$1.1 billion (improved 25% year over year)

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC — https://www.cnbc.com/2026/10/28/ford-motor-f-earnings-q3-2026.html — and Zacks and Motley Fool coverage of the earnings call.

  • Chipotle Shares Jump 7% as CEO Says Sales Growth Will Continue

    Chipotle Shares Jump 7% as CEO Says Sales Growth Will Continue

    Introduction

    Chipotle’s latest results were mixed on paper: profit missed expectations, but sales beat them. Investors focused on the sales — and on what the CEO said about the rest of the year — and sent the shares up about 7% in after-hours trading.

    What Happened

    For the third quarter of 2026, Chipotle reported revenue of $3.29 billion, up 9.6% from a year earlier and in line with expectations. Same-store sales — sales at restaurants open at least 13 months — rose 2.1%, beating the 1.5% analysts had expected, helped by a 1.3% increase in the average check. It was the chain’s third straight quarter of same-store sales growth.

    Profit was the weak spot. Net income fell to $339.9 million, or 27 cents per share, from $382.1 million, or 29 cents, a year earlier. Adjusted earnings of 27 cents per share also missed the 29 cents analysts forecast. The restaurant-level operating margin narrowed to 23.3% from 24.5%, as beef and freight costs rose.

    The shares still jumped about 7% after the report. The reason was the outlook: CEO Scott Boatwright said sales trends, which softened in early October, had returned to growth, and that he felt “very confident that November and December set up very well for us.” The company expects fourth-quarter same-store sales growth of about 2%, and executives later said they expect to exit the quarter with comparable sales up around 3% to 4%.

    Why It Happened

    Chipotle’s recovery has been built on getting customers back through the door. The company says lower-income customers are spending more at its restaurants, and its “Recipe for Growth” plan — new menu items, digital improvements, and marketing — is gaining traction. Transactions rose 0.8%, the third straight quarter of positive transaction growth, after a difficult 2025 in which same-store sales fell for the full year.

    At the same time, costs are biting. Higher beef prices and freight charges, partly linked to soaring diesel prices, pushed margins down. Chipotle raised menu prices by 2.7% in the quarter to help offset inflation, and plans another increase of about 3% in the fourth quarter.

    Why It Matters

    Chipotle is a useful test of the everyday consumer. Its customers are not luxury shoppers — they are ordinary people deciding whether a burrito is worth it that week. When same-store sales and transactions both rise, it suggests consumers are still willing to spend on small treats, even while watching prices elsewhere.

    The market reaction also shows what investors care about right now: direction, not just the quarter’s profit. A profit miss would normally hurt a stock. But a CEO credibly saying the final two months look strong was enough to outweigh it — though at least four brokerages still cut their price targets, a reminder that not everyone is convinced.

    What Happens Next

    Chipotle kept its full-year forecast for low-single-digit same-store sales growth. For 2027, it plans to open 340 to 360 company-owned restaurants in the US and Canada, plus 15 to 25 international locations. It is also bringing back smoked brisket for a limited time from November 5, timed for the holiday and football season.

    The key watch item is margins. If beef and freight costs keep rising faster than menu prices, profit will stay under pressure even as sales grow. The fourth quarter, with its price rises and holiday traffic, will show whether Chipotle can grow sales and protect profit at the same time.

    Final Thoughts

    This was a “good enough” quarter that became a good day for the stock because of the outlook. Sales beat expectations, traffic is growing again, and the CEO is confident about the holidays. But profit missed and margins shrank — the recovery is real, but it is not yet cheap to deliver.

    Key figures

    • Revenue: $3.29 billion, up 9.6% (in line with expectations)
    • Same-store sales: +2.1% (expected: +1.5%)
    • Adjusted EPS: $0.27 (expected: $0.29)
    • Net income: $339.9 million, down from $382.1 million
    • Restaurant-level margin: 23.3% (was 24.5%)
    • Q4 same-store sales guidance: ~2%
    • Shares: up ~7% in after-hours trading

    Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice.

    Sources: CNBC — https://www.cnbc.com/2026/10/28/chipotle-mexican-grill-cmg-q3-2026-earnings.html — and Reuters coverage of the results.

Is this your new site? Log in to activate admin features and dismiss this message
Log In